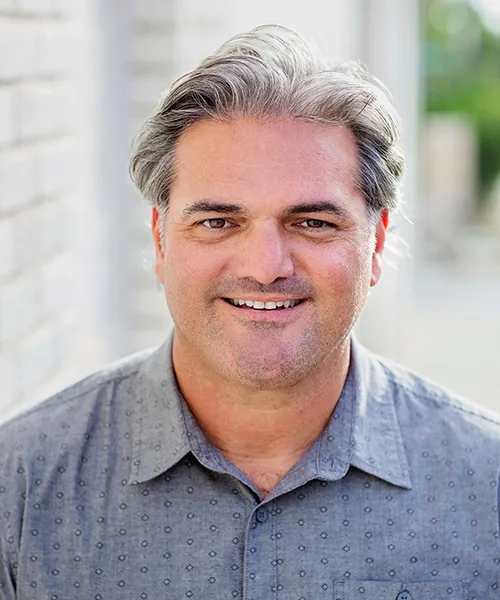
Certified Reverse Mortgage Professional With 18 Years of Experience
I'm Jay Zayer, a Certified Reverse Mortgage Professional (CRMP) and mortgage professional who has spent the past 18 years helping homeowners understand and evaluate reverse mortgages.
I created Reverse Mortgage Coach because I saw a problem that kept coming up again and again: people had questions about reverse mortgages, but they often couldn't get straightforward answers without feeling like someone was trying to sell them something.
I believe homeowners deserve to understand both the benefits and the risks before making a decision.
That's what I try to do every day.
My role isn't to convince someone that a reverse mortgage is right for them. It's to help them understand their options well enough to decide whether it actually makes sense for their situation.
Why I Specialize in Reverse Mortgages
Reverse mortgages are more complicated than many people realize.
There isn't just one type of reverse mortgage, and there isn't one strategy that works for every homeowner.
Over the years, I've worked with homeowners in very different situations. Some are looking for additional monthly cash flow. Others want to eliminate an existing mortgage payment. Some want to use home equity to purchase a new home. Others have substantial equity in a higher-value property and need to look beyond the traditional FHA-insured HECM.
I've also worked with homeowners who have a mortgage with a very low interest rate and don't want to give it up simply to access their home equity. In some situations, a reverse mortgage second may be worth exploring.
That's one of the reasons I believe homeowners should understand the different options before deciding whether a reverse mortgage is appropriate.
The right question isn't simply, "Can I get a reverse mortgage?"
The better question is:
"Which, if any, reverse mortgage strategy makes sense for what I'm trying to accomplish?"
My Approach: Education Before a Decision
A reverse mortgage is a significant financial decision, and I don't think anyone should make that decision because a salesperson made it sound easy.
I try to explain things in plain English.
That includes explaining:
- How much a homeowner may be able to access
- How the different types of reverse mortgages work
- Interest rates and how interest accumulates
- Closing costs and other fees
- What happens to the existing mortgage
- Whether monthly mortgage payments are required
- How the loan balance can change over time
- What happens when the homeowner sells the home
- What happens when the last borrower permanently leaves the home
- What happens to the home and loan when the borrower dies
- How heirs may be affected
- Property tax and homeowners insurance obligations
- The circumstances that can cause a reverse mortgage to become due
- The potential advantages and disadvantages of using home equity
And if I don't think a reverse mortgage is a good fit, I'll say that too.
There are situations where keeping an existing mortgage, selling the home, downsizing, using a traditional loan, or simply doing nothing may be the better choice.
A reverse mortgage isn't automatically the answer just because someone has equity in their home.
My Reverse Mortgage Expertise
My practice is focused on reverse mortgage lending and the different ways homeowners can potentially use their home equity.
That includes helping homeowners understand and compare:
FHA-Insured HECM Reverse Mortgages
The Home Equity Conversion Mortgage (HECM) is the FHA-insured reverse mortgage program and remains one of the most widely used reverse mortgage options.
Proprietary and Jumbo Reverse Mortgages
For homeowners with higher-value homes, proprietary reverse mortgage programs can sometimes provide options that aren't available through the standard HECM program.
Reverse Mortgage for Purchase
A HECM for Purchase can allow eligible older homeowners to use a reverse mortgage when purchasing a new primary residence.
This can be particularly interesting for homeowners who want to move without taking on a traditional monthly mortgage payment.
Reverse Mortgage Refinancing
In some situations, a homeowner who already has a reverse mortgage may benefit from evaluating whether refinancing could accomplish a particular goal.
That decision requires looking carefully at the existing loan, the current property value, the homeowner's age and circumstances, available programs, and the costs involved.
Reverse Mortgage Seconds
A reverse mortgage second is an option that many homeowners have never heard of.
In certain situations, it may allow a homeowner to access some of their home equity while keeping an existing first mortgage in place.
This can be particularly relevant for homeowners who have a very low interest rate on their current mortgage and don't want to replace it.
High-Value Homes
Homeowners with substantial equity or higher-value properties often have different considerations than someone with a more modestly priced home.
I help homeowners understand when a proprietary reverse mortgage may be worth comparing with an FHA-insured HECM and when another strategy may make more sense.
I Work With Multiple Lenders
One of the reasons I built Reverse Mortgage Coach around education and comparison is that reverse mortgage programs aren't all the same.
Different lenders can have different underwriting requirements, interest rates, lending limits, property guidelines, and product options.
Because I work with multiple lenders, I can compare available options rather than assuming that one reverse mortgage program is appropriate for everyone.
That doesn't mean there will always be a better option.
Sometimes the best answer is that the homeowner should not take out a reverse mortgage at all.
The goal is to find out.
Who I Help
I work primarily with homeowners who are approaching or in retirement and want to better understand what their home equity can and cannot do for them.
That includes homeowners who are:
- Considering a reverse mortgage for the first time
- Trying to reduce or eliminate a monthly mortgage payment
- Looking for additional retirement cash flow
- Interested in accessing home equity without selling their home
- Considering purchasing a different home
- Living in a higher-value property
- Holding a very low-rate first mortgage
- Exploring a reverse mortgage second
- Comparing an HECM with a proprietary reverse mortgage
- Trying to understand how a reverse mortgage could affect their spouse or heirs
- Simply trying to determine whether a reverse mortgage makes sense at all
I also work with professionals who advise older homeowners, including financial professionals, real estate professionals, attorneys, and other retirement and housing professionals.
Why I Created Reverse Mortgage Coach
I wanted to build something different from a typical mortgage website.
Instead of simply putting up a few pages explaining what a reverse mortgage is, I wanted to create a place where homeowners could actually get answers to the questions they have.
That's why the site includes educational articles, calculators, videos, frequently asked questions, and thousands of questions and answers covering different reverse mortgage situations.
You can also use Ask Coach Jay to ask a reverse mortgage question and get an educational answer.
My goal is simple: make reverse mortgages easier to understand.
There is already plenty of information online about reverse mortgages. The problem is that a lot of it is either overly simplistic, outdated, written to sell a product, or difficult for the average homeowner to understand.
I want Reverse Mortgage Coach to be a place where homeowners can come to learn first and make a decision second.
My Experience as a Reverse Mortgage Professional
I've spent 18 years in the mortgage industry, with my professional focus heavily centered on reverse mortgages.
I've seen the questions homeowners ask before they ever become comfortable enough to consider a loan.
I've also seen the questions that come later:
- "Will I still own my home?"
- "Do I still have to pay property taxes?"
- "What happens to my kids?"
- "Will I lose my Social Security?"
- "What happens if I need to move?"
- "How does the interest work?"
- "Can I keep my existing mortgage?"
- "Is there a way to access my equity without refinancing my first mortgage?"
- "Is a reverse mortgage actually right for me?"
Those questions are important.
I don't think homeowners should feel embarrassed for asking them. In fact, asking a lot of questions is exactly what I encourage.
My Professional Credentials
I am a Certified Reverse Mortgage Professional (CRMP).
The CRMP designation is specifically focused on reverse mortgage knowledge and professional standards.
I am also a licensed mortgage professional and real estate broker.
I am licensed in California and Arizona.
NMLS: 307713
California Department of Real Estate: 01456165, 01450361
Arizona: 1022722
I maintain my professional licensing and credentials so homeowners can verify who I am and the capacity in which I work.
Serving Homeowners in California and Arizona
Reverse Mortgage Coach serves homeowners throughout California and Arizona.
I work with homeowners in San Diego County and throughout California, as well as homeowners across Arizona.
Because reverse mortgage eligibility and available programs can depend on the homeowner, property, location, and other circumstances, I encourage homeowners to look at their individual situation rather than relying on a general example they find online.
What I Believe About Reverse Mortgages
I don't believe reverse mortgages are right for everyone.
I also don't believe they're the "scam" that some people make them out to be.
Like other financial products, they have legitimate uses, costs, requirements, benefits, and risks.
The important thing is understanding what you're actually getting into.
A reverse mortgage can be a useful retirement planning tool for the right homeowner.
It can also be an expensive or inappropriate choice for the wrong homeowner.
That's why I don't start with the loan.
I start with the homeowner.
What are you trying to accomplish?
What other options do you have?
What are the trade-offs?
What happens five or ten years from now?
And what happens if your plans change?
Those are the questions I believe should come before deciding on any reverse mortgage.
A Little About Me
Outside of mortgages, I'm a husband, father, and longtime youth football and soccer coach.
Coaching has probably influenced the way I work more than I realized.
Good coaching isn't about telling someone what decision to make. It's about giving them the information, perspective, and confidence to make a good decision themselves.
That's the same approach I try to bring to my work with homeowners.
Published and Featured Expertise
I regularly write and contribute information about reverse mortgages and retirement housing strategies.
My work has also been published by HousingWire.
As Reverse Mortgage Coach grows, I'll continue adding interviews, articles, educational resources, and other places where my work and expertise have been featured.
Have a Reverse Mortgage Question?
You don't have to know whether you want a reverse mortgage before asking questions.
In fact, I would rather you ask questions first.
If you're considering a reverse mortgage, trying to understand an existing reverse mortgage, or simply wondering whether there is a better way to use the equity in your home, start by learning your options.
You can explore the educational resources on Reverse Mortgage Coach or ask Coach Jay your specific question.
And if a reverse mortgage isn't the right answer for you, that's an important answer too.
Learn your options. Understand the trade-offs. Then decide.
That's what Reverse Mortgage Coach is here to help you do.